Synthetic identity fraud combines genuine personal data with invented details to create a person who does not exist. Its slow, patient approach makes it difficult for lenders, benefit agencies and identity systems to spot before losses emerge.
A PEP result is a prompt to understand risk, not a verdict on a customer. UK guidance includes domestic officeholders, their relatives and close associates, and offers no simple date on which the heightened review can end.
Liveness detection is designed to distinguish a person standing in front of a camera from a fraudulent representation of that person. Its value depends on the attack it is built to detect, the way it is tested and the controls around the camera feed.
I have watched live streaming develop from a collection of individual platforms into a much larger entertainment industry where discovery matters almost as much as the performances themselves.
Selective disclosure can let someone prove they are old enough for an online service without sending a copy of a passport or driver’s licence. It offers a possible middle ground as age-assurance rules collide with concerns about routine identity collection.
Online gambling operators are judged not only on games and payments but on whether they can identify customers, keep minors out and intervene when play becomes harmful. Across regulated markets, those controls are increasingly treated as conditions of a licence, not back-office compliance.
New account fraud begins before a customer has anything to lose: a criminal creates an account using a stolen, synthetic or manipulated identity. The quality of checks at onboarding often determines whether later fraud can be prevented or merely contained.
I have watched adult marketing change as platforms face greater expectations around age assurance, content access, and minor protection. From my perspective at Allinid, TopChats offers an interesting response to that challenge.
The EU's payment-law revision puts identity checks closer to the center of fraud prevention and liability. Its most concrete verification measure is an IBAN-to-name check designed to stop misdirected and impersonation-scam payments.
Mobile driver's licences are moving from pilot programs toward practical use, but a shared technical standard has not yet produced universal acceptance. ISO 18013-5 gives issuers and readers a secure way to exchange credential data, while leaving major operational and privacy questions unresolved.
Identity verification systems do not need to become permanent archives of passports, selfies and address records. Data minimization can reduce privacy and breach risk while preserving the evidence needed for a specific decision.
I have seen live cam directories become increasingly useful as the number of streaming platforms available to consumers continues to grow. At Allinid, I believe discovery should be simple, organized, and safe for people who do not want explicit material appearing unexpectedly on their screens.
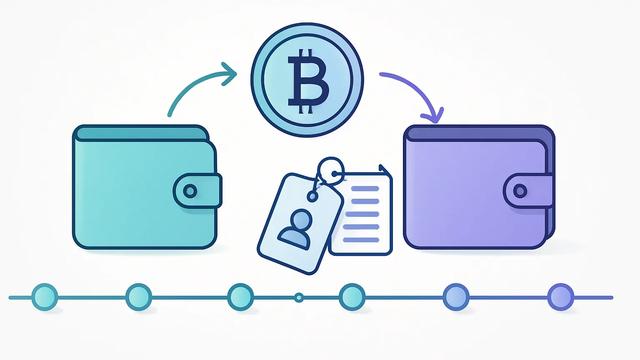
The FATF Travel Rule brings bank-style sender and recipient data obligations to many crypto transfers. Its spread is pushing exchanges toward shared compliance infrastructure while testing the limits of decentralized finance.
Injection attacks bypass the phone or webcam at the center of remote identity verification. Rather than presenting a fake face to a lens, fraudsters can feed prepared imagery directly into the software path meant for a live capture.
NIST’s updated digital identity guidance raises the bar for proving who is online, securing sign-ins and sharing identity data. Its influence will extend beyond US federal agencies, but it is not a blanket private-sector mandate.
Near-field communication lets a phone inspect the signed data inside an electronic passport, adding a cryptographic check to remote identity verification. It can materially improve document assurance, but it does not eliminate operational and coverage gaps.
Illinois' Biometric Information Privacy Act has made face, fingerprint and voice data a major litigation risk. Its influence now reaches far beyond the state, even as US biometric rules remain fragmented.
Acquisitions are reshaping identity verification into broader platforms that combine document checks, biometrics, fraud controls and compliance tools. The shift can simplify procurement, but it also raises switching costs and concentration concerns.
 Fraud & Threats